Every trading day, a few numbers appear on a handful of websites that Bitcoin watchers check almost as closely as the price itself: the net flows into and out of U.S. spot Bitcoin ETFs. When the number is large and positive, headlines celebrate. When it turns negative, people start asking whether the rally is over.
Why do those numbers get so much attention? Because Bitcoin ETFs changed who can easily gain exposure to Bitcoin, how that exposure can be accessed, and how quickly demand from traditional investment accounts can enter the market. This guide explains the connection between ETFs and Bitcoin's price, what recent data shows, and, just as importantly, where the connection stops.
This article is educational, not financial advice. Bitcoin is volatile, and ETF flow data is only one input among many.
The Short Answer
Bitcoin ETFs matter for Bitcoin's price for three main reasons:
- 1. They make Bitcoin exposure easier to access. Many investors can buy shares through a brokerage account without opening a crypto exchange account or managing a wallet.
- 2. They create a visible measure of investment demand. Daily flow estimates and fund activity give traders another way to see whether capital is moving into or out of U.S. spot Bitcoin products.
- 3. They connect Bitcoin more closely to traditional finance. Financial advisors, institutions, retirement accounts, and other investors that may not want or be able to hold Bitcoin directly have a familiar way to gain price exposure.
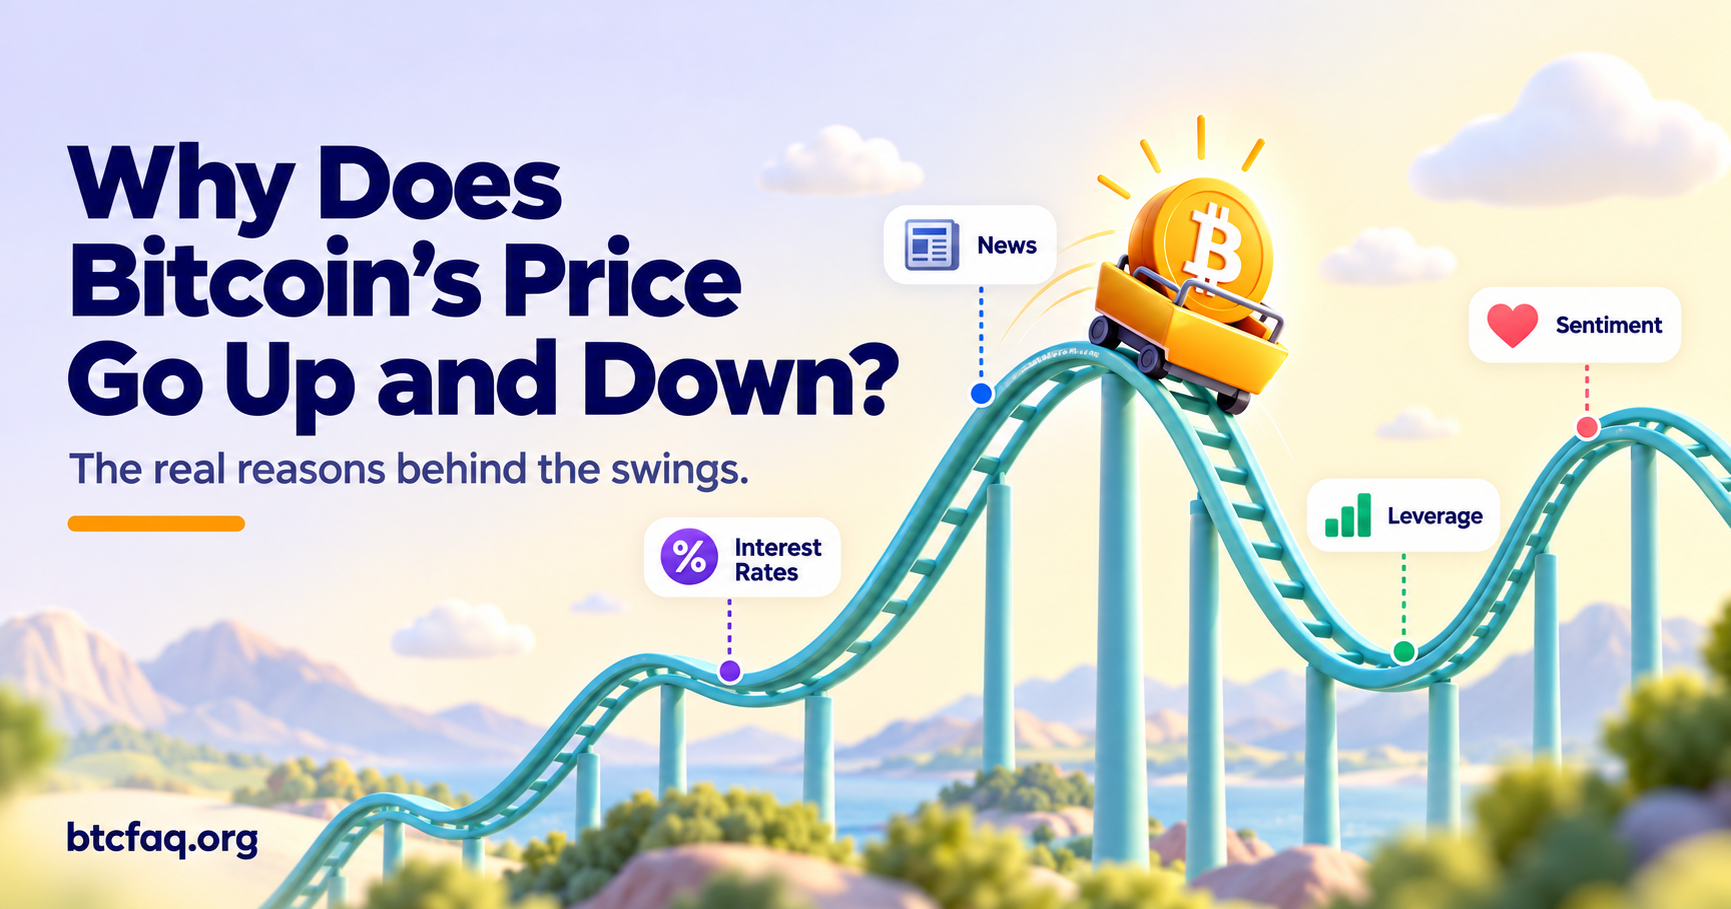
But ETFs are a channel for demand, not the source of it. They can amplify a move in either direction, and they are one force among several, including interest rates, leverage in the derivatives market, and plain sentiment.
A Quick Refresher: How a Spot Bitcoin ETF Works
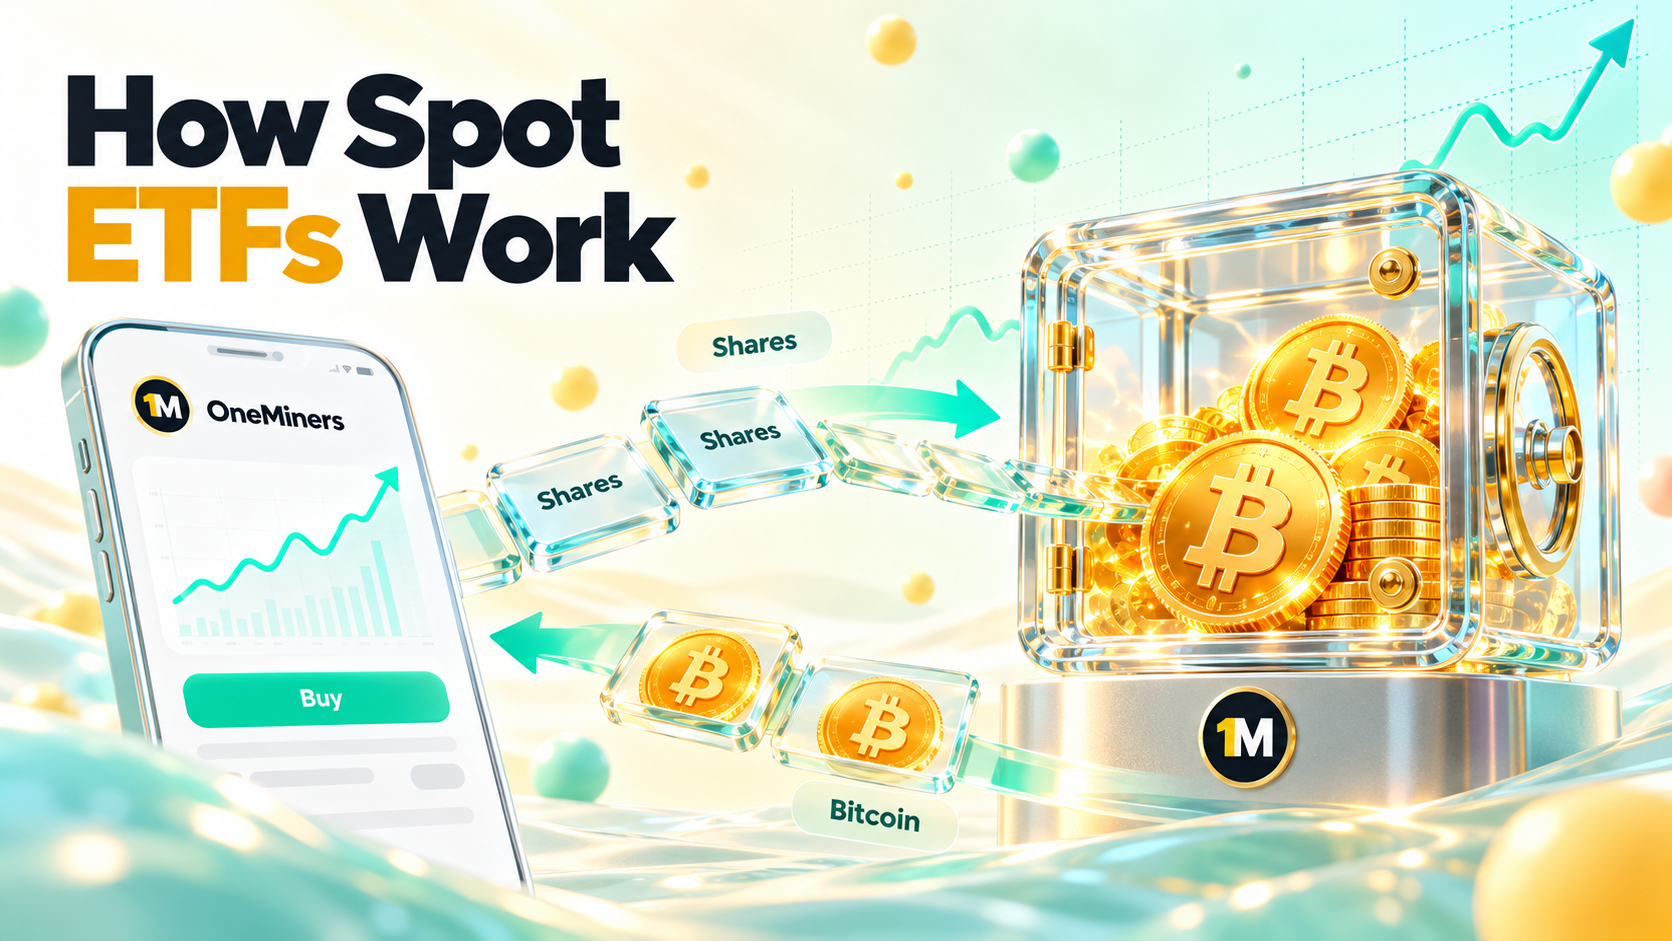
A U.S. spot Bitcoin exchange-traded product, commonly called a spot Bitcoin ETF, holds Bitcoin as its underlying asset and trades on a stock exchange. Retail investors normally buy and sell the shares through a brokerage. Behind the scenes, authorized participants create or redeem large blocks of shares. Since July 2025, the SEC has permitted crypto ETPs to use in-kind creations and redemptions as well as cash-based processes, meaning Bitcoin can sometimes be transferred directly rather than the issuer having to buy or sell it on the open market. A custodian holds the Bitcoin backing the product. If you want the full comparison between owning an ETF and owning Bitcoin itself, see our guide on Bitcoin ETFs versus buying Bitcoin.
That structure is why ETF flows can still matter for Bitcoin's market. Net creations indicate demand for ETF shares and can lead authorized participants or other market participants to source or transfer Bitcoin to support new shares. Net redemptions can work in the opposite direction. But the relationship is not perfectly mechanical: a reported $1 billion inflow does not necessarily mean a fund manager went into the open market and bought exactly $1 billion of Bitcoin that day, and an outflow does not always require an immediate Bitcoin sale.
How ETFs Can Influence Bitcoin's Price
1. Demand meets a limited supply
Bitcoin's maximum supply is capped at 21 million coins, and new coins are issued on a predetermined schedule. Since the 2024 halving, miners receive a block subsidy of 3.125 BTC per block, which works out to roughly 450 newly issued bitcoin per day before considering transaction fees.
Large ETF demand matters because creation activity can increase demand for the underlying Bitcoin. Depending on how shares are created, authorized participants may source Bitcoin from the market or transfer coins they already hold. When the Bitcoin needed to support investment demand exceeds newly mined supply, the additional coins ultimately have to come from existing holders or other available inventories. That can contribute to upward price pressure when sellers demand higher prices, although the effect is not automatic or one-to-one.
The reverse can happen during sustained redemptions. Bitcoin returned through the redemption process may eventually become available to the market or contribute to selling pressure, but an ETF outflow does not necessarily mean the same amount of Bitcoin is immediately sold on an exchange.
2. A bigger pool of potential buyers
Before spot ETFs, buying Bitcoin meant opening an account on a crypto platform, learning about wallets and keys, and trusting a new type of company. For many financial advisors, pension funds, and everyday investors, that was a barrier. ETFs lowered it. The same brokerage account used for stocks and funds can now hold Bitcoin exposure. A larger pool of people who can buy is a structural change in potential demand, even if it doesn't guarantee they will.
3. Legitimacy and the "signal" effect
Large, regulated, well-known financial firms offering Bitcoin products send a signal that Bitcoin has become more integrated with traditional financial markets. That perception may encourage some cautious investors who were previously uncomfortable buying Bitcoin through crypto-native platforms. The effect is difficult to measure separately from price, regulation, and broader market sentiment, so it is better viewed as one possible contributor to adoption rather than proof that ETF availability itself causes prices to rise.
4. Flows as a sentiment gauge
Daily and weekly flow data has become a shorthand for how institutions and advisors feel. Strong inflows get read as confidence. Persistent outflows get read as caution. Because so many traders watch the same numbers, the data can influence behavior on its own, and a sharp reversal in flows can make a market nervous even before it changes the supply and demand math.
5. Interaction with the derivatives market
ETF buying doesn't happen in isolation. Futures and perpetual-swap markets, where traders bet with leverage, can move with or against ETF flows. As we'll see in the data below, it's possible for ETF buyers to push the price up while leveraged traders sell into the move, or for the opposite to happen. The final price is the net result of all these forces colliding.
What the Data Shows Right Now
Here's a look at recent evidence, with each figure attributed to its source.
A strong inflow week in late September
Glassnode's Week 40 Bitcoin Market Pulse covers the week ending 27 September 2026. It reports that U.S. spot ETF net flows rose to about $2.7 billion for the week, up from roughly $575 million a week earlier and well above the metric's usual high range. Bitcoin touched about $87,000 midweek, sat near $84,000 at the start of the following week, and closed the week about 4% higher.
The report's own summary captures the dynamic well: ETF inflows and fresh capital carried the gain, while perpetual-futures traders and profit-takers sold into it. In other words, ETF demand was strong enough to lift the price even though other market participants were selling, which is exactly the kind of tug-of-war described above.
A related snapshot comes from OneMiners' Uptober 2026 article, written by the company's CEO and published on 5 October 2026. It highlighted a sustained run of positive U.S. spot Bitcoin ETF flows through late September, with Bitcoin starting October near $83,700. The article also points to Bitcoin's seasonal record: it says Bitcoin closed October higher in 10 of the previous 13 years, with a median gain of about 15%, while stressing that “history is a tailwind, not a promise.” Because the piece is published by a Bitcoin mining and hosting company and includes promotional material, it is best used as one source alongside independent market data rather than as a forecast.
Then the flows cooled and turned negative
Check the daily table at Farside Investors, which tracks U.S. spot Bitcoin ETF flows, and the picture for October looks different. After a positive first week of the table's window (28 September to 2 October), the following two weeks were mostly negative:
- • 7 October: about $485 million in net outflows
- • 8 October: about $244 million in net outflows
- • 13 October: about $176 million in net inflows
- • 14 October: about $261 million in net outflows
- • 16 October: about $82 million in net outflows, driven mainly by BlackRock's IBIT and Fidelity's FBTC
Adding up the ten most recent trading days in that table (5 to 16 October), flows were net negative by roughly $900 million. Farside's table also shows a running total of roughly $56.9 billion in cumulative net flows, which appears to cover the funds' entire history, although the page doesn't spell out its start date. Farside also notes the data is generated automatically and may contain errors.
The takeaway is not that ETFs have "stopped working." It's that flows are volatile, and a strong week doesn't guarantee the next one. Flows are only part of the story, and it is worth checking where Bitcoin's price actually traded over the same days before drawing conclusions.
The same pattern earlier in the year
CoinShares publishes a weekly report on digital-asset investment flows across all products, not just U.S. ETFs. Its report for the week ending 11 May 2026 is a good example of how inflows build momentum. It recorded $857.9 million of total inflows, the sixth positive week in a row, including $706.1 million into Bitcoin products, with the United States accounting for $776.6 million of the total. CoinShares tied the improvement partly to optimism over proposed U.S. crypto legislation, and noted that Bitcoin rose above $80,000 that week, its highest level since a February correction.
Comparing the two periods tells a useful story: flows tend to follow the mood of the market, and they can reverse when the mood changes.
Why Flows Don't Tell the Whole Story
It's tempting to treat ETF flows as a crystal ball. Here's why that's a mistake.
Flows can lag the price. Investors often buy after a price move has already started, so some of the "demand" you see is a reaction rather than a cause.
Other forces matter just as much. Macro conditions are one example. The Federal Reserve raised its target rate by 0.25 percentage point in September 2026, its first rate increase since 2023. U.S. Treasury data also showed the 10-year Treasury yield around the low-to-mid 5% range in early October. Higher interest rates and bond yields can make riskier assets less attractive to some investors by increasing the returns available from lower-risk alternatives. The OneMiners Uptober 2026 article discusses this same macro backdrop, but ETF demand, interest rates, liquidity, leverage, and investor sentiment all interact rather than operating independently.
Leverage can swamp spot demand. Glassnode's report highlighted aggressive selling in the perpetual-futures market even as ETF buying surged. Leveraged positions can be liquidated in cascades that move the price much faster than ETF flows alone.
Price is a long way from the top. According to the OneMiners article, Bitcoin's all-time high is $126,080, set on 6 October 2025, and the price at the start of October 2026 was roughly 34% below it. Even with ETFs in place, Bitcoin has had large drawdowns, and the products don't smooth them out.
Why ETF Flows Matter to Bitcoin Miners
ETFs and price also matter to the people securing the network. Miners earn Bitcoin while paying many of their operating expenses in regular currency, so profitability is highly sensitive to Bitcoin's dollar price. This one-week data review by Cassys on Medium, published in August 2026 when Bitcoin was near $64,900, reported hashprice at roughly $28.90 to $30.60 per petahash per day and estimated the cost of producing one Bitcoin for a median miner at about $85,604—well above the market price in that particular snapshot.
Bitcoin has since moved back into the $80,000 range, narrowing that gap, but the comparison should not be treated as a universal mining breakeven point. The Cassys analysis describes its estimate in terms of median hardware and a median power contract, but it does not provide enough underlying calculation detail to reproduce the $85,604 figure independently. Treat it as an illustration of the margin pressure miners faced at that moment rather than a precise industry-wide production cost. The broader connection still holds: when a higher Bitcoin price lifts mining revenue, margins can improve; when price falls or network difficulty rises, those margins can tighten again.
How to Read ETF Flow Data Without Overreacting
If you're going to follow flows, a few habits help:
- • Look at weeks, not days. A single big day can be noise. A multi-week trend says more.
- • Compare against price. Strong inflows during a falling price tell a different story than inflows during a rally.
- • Check several sources. Farside covers daily U.S. ETF flows, CoinShares covers weekly flows across global products, and Glassnode combines flow data with on-chain and derivatives metrics.
- • Remember what's missing. ETF data doesn't capture buying on exchanges, by corporations, or by individuals holding their own coins.
- • Don't trade on one number. Flow data is context, not a signal to act on by itself.
Common Misconceptions
"ETF inflows guarantee the price will rise." They add demand, but price depends on everything else going on at the same time, including selling by other holders.
"Outflows mean Bitcoin is crashing." Outflows add selling pressure, but modest outflows can coincide with a stable price. Compare flows with the price over the same days.
"ETFs control Bitcoin's price." They're a major source of demand, but Bitcoin also trades around the clock on global exchanges and in derivatives markets.
"ETFs mean institutions own most Bitcoin." ETFs are one category among many holders, which also include individuals, companies, and early adopters.
Frequently Asked Questions
Why are Bitcoin ETFs important for Bitcoin's price? They make Bitcoin easier to buy for millions of investors, create a measurable stream of demand, and link Bitcoin to traditional finance, all of which can influence how much buying pressure the market sees.
Do Bitcoin ETF inflows push the price up? Strong net creations can increase demand for Bitcoin exposure and may require authorized participants or other market participants to source Bitcoin to support new ETF shares. That can contribute to buying pressure, but an inflow does not guarantee that an equal dollar amount of Bitcoin is immediately purchased on the open market. Whether the price actually rises depends on ETF demand relative to selling, liquidity, derivatives positioning, and other market activity.
What happens when ETFs have outflows? Net redemptions reduce the amount of capital invested in the products and can contribute to sell-side pressure. However, because crypto ETPs can use in-kind redemptions, Bitcoin may sometimes be transferred to an authorized participant rather than immediately sold into the market. Heavy or persistent outflows can still be bearish for sentiment, especially when they occur alongside selling elsewhere.
Where can I see daily Bitcoin ETF flows? Farside Investors publishes a free daily table of U.S. spot Bitcoin ETF flows. CoinShares publishes weekly fund-flow reports, and Glassnode publishes weekly market summaries that include ETF metrics.
Do ETFs make Bitcoin less volatile? Not by themselves. Recent data shows flows swinging from billions of dollars of weekly inflows to hundreds of millions of daily outflows within a few weeks.
Is October always good for Bitcoin? Not always. According to the OneMiners article, Bitcoin has closed October higher in 10 of the last 13 years, but October 2025 closed down 3.7%. Seasonality is a pattern, not a promise.
Should I buy a Bitcoin ETF because of the flows? That's a personal decision. Flow data is one of many inputs, and you may want to speak with a qualified financial professional about your own situation.
Final Thoughts
Bitcoin ETFs matter for Bitcoin's price because they changed the plumbing of investment demand. They allow a much broader group of investors to gain Bitcoin exposure through familiar brokerage accounts, and their flows provide a visible measure of how capital is moving through that part of the market. Strong creation activity can increase demand for the Bitcoin underlying those products. Because only about 450 new BTC are issued through mining each day, sufficiently large demand ultimately has to be met by coins already held elsewhere in the market.
But ETF flows are better understood as one important force than as a switch controlling Bitcoin's price. Interest rates, liquidity, derivatives leverage, sentiment, corporate and individual buying, long-term holders, and broader economic conditions all matter as well. Watch ETF flows for context, but compare them with price and the rest of the market before drawing conclusions.